Ditapis dengan
Ditemukan 6 dari pencarian Anda melalui kata kunci: author=Deborah Hughes
Preparation Cousre For the TOEFL Test
- Edisi
- -
- ISBN/ISSN
- 0131408836
- Deskripsi Fisik
- xxiii, 641 hlm.; 30 cm
- Judul Seri
- -
- No. Panggil
- 428.24 PHI p
- Edisi
- -
- ISBN/ISSN
- 0131408836
- Deskripsi Fisik
- xxiii, 641 hlm.; 30 cm
- Judul Seri
- -
- No. Panggil
- 428.24 PHI p
Understanding Computers in a Changing Society
- Edisi
- -
- ISBN/ISSN
- 9781133191117
- Deskripsi Fisik
- xvi, 374 hlm.; 27,5 cm
- Judul Seri
- -
- No. Panggil
- 004 MOR u
- Edisi
- -
- ISBN/ISSN
- 9781133191117
- Deskripsi Fisik
- xvi, 374 hlm.; 27,5 cm
- Judul Seri
- -
- No. Panggil
- 004 MOR u
Perilaku Mengajar
- Edisi
- -
- ISBN/ISSN
- 9786028555906
- Deskripsi Fisik
- 322 hlm.; 21 × 28 cm
- Judul Seri
- -
- No. Panggil
- 616.16 CRU p
- Edisi
- -
- ISBN/ISSN
- 9786028555906
- Deskripsi Fisik
- 322 hlm.; 21 × 28 cm
- Judul Seri
- -
- No. Panggil
- 616.16 CRU p
Introduction To Thermal And Fluid And Engineering
- Edisi
- -
- ISBN/ISSN
- 9781118103487
- Deskripsi Fisik
- xvi, 783 hlm,; 27 cm
- Judul Seri
- -
- No. Panggil
- 623.810 3 DEB i
- Edisi
- -
- ISBN/ISSN
- 9781118103487
- Deskripsi Fisik
- xvi, 783 hlm,; 27 cm
- Judul Seri
- -
- No. Panggil
- 623.810 3 DEB i

A Scenario Tree-Based Decomposition for Solving Multistage Stocchastic Programs
Optimization problems involving uncertain data arise in many areas of industrial and economic applications. Stochastic programming provides a useful framework for modeling and solving optimization problems for which a probility distribution of the unknown parameters is available.
- Edisi
- -
- ISBN/ISSN
- 9783834814098
- Deskripsi Fisik
- xvi, 182 hlm.; 21 cm.
- Judul Seri
- -
- No. Panggil
- 519.2 DEB a
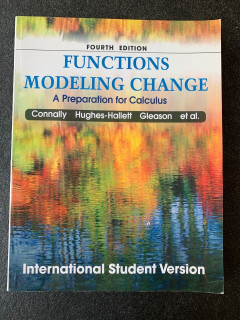
Functions Modeling Change: A Preparation or Calculus
this book is the definitive precalculuc text, providing student with a solid mathematical foundation and preparing them for a continued education in calculus. By focusing on a select number of fundamental concepts, the author have crafted a text that emphasizes depth of understanding over breadth of coverage.
- Edisi
- 4
- ISBN/ISSN
- 9780470910405
- Deskripsi Fisik
- xvi, 621 hlm.; 27 cm.
- Judul Seri
- -
- No. Panggil
- 515.1 CON f
 Karya Umum
 Filsafat
 Agama
 Ilmu-ilmu Sosial
 Bahasa
 Ilmu-ilmu Murni
 Ilmu-ilmu Terapan
 Kesenian, Hiburan, dan Olahraga
 Kesusastraan
 Geografi dan Sejarah